
Gartner expects chip growth to slow from the 2014 pace of 7.9%. From STAMFORD, Conn., January 14, 2015
Gartner Says Worldwide Semiconductor Sales Expected to Reach $358 Billion in 2015, a 5.4 Percent Increase From 2014
Compute, Wireless and Consumer Application Semiconductors Represent More Than 66 Percent of Total Semiconductor Revenue
Worldwide semiconductor revenue is forecast to reach $358 billion in 2015, a 5.4 percent increase from 2014, but down from the previous quarter's forecast of 5.8 percent growth, according to Gartner, Inc. The market is being driven by strong growth in application-specific standard products (ASSPs) in smartphones, along with DRAM and NAND flash in ultramobiles and solid-state drives (SSDs).
"Semiconductor revenue growth in 2015 is expected to slow from the 7.9 percent growth experienced in 2014 as DRAM returns to more traditional price reductions and the industry burns off excess holiday inventory," said Jon Erensen, research director of Gartner. "DRAM pricing was unusually firm in 2014 due to short supply, which propelled DRAM to be the fastest-growing device type in 2014 with 31.7 percent revenue growth. DRAM supply and demand will be in line in 2015, driving bit pricing down a more traditional 16.8 percent and reducing annual DRAM revenue growth to 7.7 percent."
From an application point of view, smartphones, SSDs and ultramobiles will see the largest dollar increases. In 2015, compute applications will continue to be the largest market for semiconductors, followed by wireless and consumer applications. Combined, these three device categories represent more than two-thirds of total semiconductor revenue and have the most influence on the overall strength of the semiconductor market.
However, in 2015, the industrial electronics segment is expected to outperform overall semiconductor market growth and other electronic application categories with revenue growth of 9.1 percent. The growth will be driven mainly by LED lighting applications for industrial and residential purposes and smart city projects. In addition, the Internet of Things (IoT) will continue to drive very strong unit growth in 2015 and beyond.
Following industrial applications, wireless applications — driven mainly by mobile phones — will be the next biggest growth market for semiconductors in 2015. However, the 2015 revenue growth forecast for wireless applications, and specifically mobile phones, remains the same as the previous quarter's forecast.
"While mobile phone semiconductor sales will remain robust, driven by the accelerating shift to smartphones and 4G Long Term Evolution, there is concern that weak sell-through for other electronic equipment categories will result in higher inventory levels and drag down semiconductor sales in the first quarter of 2015," said Mr. Erensen.
Showing posts with label Gartner Semiconductor Revenue. Show all posts
Showing posts with label Gartner Semiconductor Revenue. Show all posts
Wednesday, January 14, 2015


Friday, December 14, 2012
Gartner Semiconductor Chip Forecasts Cut for 2012 and 2013
Amid "ongoing economic and political uncertainty", yesterday Gartner lowered its growth projections for the global semiconductor market in 2012 and 2013, citing "economic headwinds and an inventory correction."
Press Release:
Gartner Says Worldwide Semiconductor Sales to Reach $311 Billion in 2013, a 4.5 Percent Increase from 2012
Semiconductor Growth Forecast Revised Down Amid Ongoing Economic and Political Uncertainty
STAMFORD, Conn., December 13, 2012— Worldwide semiconductor revenue is projected to total $311 billion in 2013, a 4.5 percent increase from 2012 revenue, according to Gartner, Inc. Due to economic headwinds and an inventory correction, the fourth quarter projections have been revised down from the previous quarter's forecast of $330 billion.
Analysts have also reduced growth predictions for 2012 with semiconductor revenue expected to total $298 billion, down 3 percent from 2011. Gartner's third quarter forecast had put revenue at $309 billion for 2012, which would have meant an increase of 0.6 percent from 2011.
"The looming fiscal cliff, ongoing European debt crisis, slower emerging market growth and regional tensions have all played a part in reduced growth projections for semiconductor revenue in both 2012 and 2013," said Peter Middleton, principal analyst at Gartner. "Inventory levels were already high at the start of the second half of 2012, and as PC demand rolled off, supply simply overshot demand."
The semiconductor market was further depressed when DRAM prices failed to rebound in 2012. Gartner predicts that the DRAM market will not recover until the second half of 2013, when lower supply growth is expected to pull the market into a period of undersupply. This should prove a turning point for the semiconductor industry; memory is expected to lead the recovery with 15.3 percent growth and total semiconductor revenue is projected to reach $342 billion in 2014, an increase of 9.9 percent from 2013.
The "Apple effect" is expected to remain pronounced in 2013, helping drive strong NAND and application-specific integrated circuit (ASIC) revenue growth of 17.2 percent and 9.4 percent, respectively. Gartner counts the A4, A5 and A6 application processors from Apple as ASICs, because these are custom processors, designed and solely used by Apple. ASICs will also benefit from the new generation of video game consoles being introduced in late 2012 and 2013.
PC production will decline 2.5 percent in 2012. In 2013, total PC production is expected to remain weak; however, ultramobile PCs will grow strongly off a small base. The challenging economic environment has contributed to PC life cycle extension, in addition to users extending the life of their PCs as they adopt tablets.
Mobile phone production growth in 2012 and 2013 is predicted to soften overall as the tough economy reduces short-term demand for phones. However, the forecast for utility/basic smartphones has been increased, largely at the expense of traditional phones. In particular, adoption of Android-based entry-level smartphones in emerging regions continues to accelerate and will be a key growth driver. Worldwide smartphone unit production growth in 2013 is forecast to be 33 percent.
Media tablet production is also forecast to grow in 2013, rising 38.5 percent to 207.1 million units, up from the third quarter forecast of 169.8 million units. The success of the Amazon Kindle Fire, Google Nexus 7 and Apple iPad Mini illustrate the large opportunity for smaller tablets at the right price, while the white-box tablet market is stronger than anticipated, boosting the overall forecast.
Read more about Gartner at the Press Release:
Thursday, December 09, 2010
2010 Semiconductor Vendor Sales Ranking
Top Ten Worldwide Semiconductor Vendors
* NEC Electronics was renamed Renesas Electronics in 2Q10. This name change has been applied retrospectively to 2009 to maintain continuity. Renesas Electronics acquired Renesas Technology in 2Q10. According to Gartner's merger and acquisition policy (restated in December 2009), Renesas Technology's revenue has been attributed to Renesas Electronics for 2Q10 through 4Q10. NEC Electronics' 1Q10 revenue has been attributed to Renesas Electronics for 2010, while Renesas Technology's 1Q10 revenue ($1,731 million) has been accounted for separately.
** Micron's revenue includes partial revenue from Numonyx, which it acquired in early 2010.
Source: Gartner Says Worldwide Semiconductor Revenue Increased 31.5 Percent in 2010 to Exceed $300 Billion
Preliminary Ranking by Estimated Revenue
Rank 2009 | Rank 2010 | Company | 2009 Revenue US$M | 2010 Revenue US$M | 2009-2010 Growth (%) | 2010 Market Share (%) |
| 1 | 1 | Intel | 33,253 | 41,430 | 24.6 | 13.8 |
| 2 | 2 | Samsung Electronics | 17,686 | 28,256 | 59.8 | 9.4 |
| 3 | 3 | Toshiba | 9,604 | 12,376 | 28.9 | 4.1 |
| 4 | 4 | Texas Instruments | 9,142 | 12,356 | 35.2 | 4.1 |
| 11 | 5 | Renesas Electronics* | 4,542 | 10,368 | 128.3 | 3.5 |
| 7 | 6 | Hynix Semiconductor | 6,035 | 10,350 | 71.5 | 3.4 |
| 5 | 7 | STMicroelectronics | 8,510 | 10,290 | 20.9 | 3.4 |
| 13 | 8 | Micron Technology ** | 4,170 | 8,884 | 113.0 | 3.0 |
| 6 | 9 | Qualcomm | 6,409 | 7,167 | 11.8 | 2.4 |
| 10 | 10 | Infineon | 4,682 | 6,680 | 42.7 | 2.2 |
| Others | 124,338 | 152,156 | 22.4 | 50.7 | ||
| Total | 228,371 | 300,313 | 31.5 | 100.0 |
* NEC Electronics was renamed Renesas Electronics in 2Q10. This name change has been applied retrospectively to 2009 to maintain continuity. Renesas Electronics acquired Renesas Technology in 2Q10. According to Gartner's merger and acquisition policy (restated in December 2009), Renesas Technology's revenue has been attributed to Renesas Electronics for 2Q10 through 4Q10. NEC Electronics' 1Q10 revenue has been attributed to Renesas Electronics for 2010, while Renesas Technology's 1Q10 revenue ($1,731 million) has been accounted for separately.
** Micron's revenue includes partial revenue from Numonyx, which it acquired in early 2010.
Source: Gartner Says Worldwide Semiconductor Revenue Increased 31.5 Percent in 2010 to Exceed $300 Billion
Sunday, September 05, 2010
Gartner Worldwide Semiconductor Revenue Latest Prediction & History
01 Sept 2010 [Predicts $314B for 2011] Worldwide semiconductor revenue in 2010 is forecast to reach $300 billion, a 31.5 per cent increase from 2009 revenue of $228 billion, according to the latest outlook by Gartner, Inc. Analysts project worldwide semiconductor revenue to total $314 billion in 2011, a 4.6 per cent increase from 2010.
(press Release) [2010 actual tbd]
03 June 2010 [Predicts $307B for 2011] Worldwide chip revenue is forecast to reach $290 billion in 2010, a 27.1 percent increase from 2009 revenue of $228 billion, according to Gartner, Inc. The outlook for the semiconductor industry has improved from Gartner's first quarter 2010 forecast, when it projected worldwide semiconductor sales to grow 19.9 percent. Gartner analysts expect the semiconductor industry to show continued growth through its forecast period in 2014. The market is on track to surpass the $300 billion mark in 2011, when the market is forecast to total $307 billion.
(Story at EE Times) [2010 actual tbd]
16 November 2009 [predicts $255B for 2010] Worldwide semiconductor revenue is on pace to total $226 billion in 2009, an 11.4 percent decline from 2008 revenue of $255 billion, according to the latest outlook by Gartner, Inc... Semiconductor revenue in 2010 is expected to bounce back to the same revenue level as 2008 at $255 billion, a 13 percent increase from 2009.
(Press Release) [2010 actual tbd]
26 August 2009 [Predicts $233B for 2010] Worldwide semiconductor revenue is on track to total $212 billion in 2009, a 17.1 percent decline from 2008 revenue of $255 billion, according to the latest outlook by Gartner, Inc. This forecast is better than the second quarter projections when Gartner projected semiconductor revenue to decline 22.4 percent this year. ... Gartner’s latest outlook for 2010 is worldwide semiconductor revenue to total $233 billion, a 10.3 percent increase from 2009 projections.
(Press Release) [2010 actual tbd]
03 Sept 2008 [Predicts $308B for 2009] Gartner said it now expects overall 2008 semiconductor revenue to be $285 billion, an increase of 4.2 percent over 2007. The firm had most recently projected chip revenue to be 4.6 percent for the year, reaching $287 billion. Gartner lowered its 2009 revenue projection to $308 billion, up 7.8 percent from 2008. The firm's earlier projection called for 2009 revenue to increase 7.9 percent to $309 billion.
(Story at EE Times) [2009 actual $218.5B]
05 May 2007 [Predicts $293B for 2008 & $314B for 2009] Gartner Inc. has lowered its 2007 worldwide semiconductor forecast to $269.2 billion, a 2.5 percent increase from 2006. In Gartner's previous forecast, it predicted a 2007 revenue increase of 6.4 percent. Gartner expects the worldwide semiconductor industry to return to modest annual growth of 8.7 percent and 7.2 percent in 2008 and 2009, respectively.
(Story at EE Times)
- 2008: 1.087x$269B = $293B
[2008 actual $256.0B] - 2009: 1.072x$293B = $314B
[2009 actual $218.5B]
| Year | Worldwide Semiconductor Revenue | Worldwide Semiconductor Revenue | Yr/Yr Change |
| x1,000 | $B | ||
| 1990 | $50,025,208 | 50.0 | |
| 1991 | $54,449,772 | 54.4 | 8.8% |
| 1992 | $59,016,977 | 59.0 | 8.4% |
| 1993 | $75,654,012 | 75.7 | 28.2% |
| 1994 | $99,168,072 | 99.2 | 31.1% |
| 1995 | $140,689,092 | 140.7 | 41.9% |
| 1996 | $134,176,361 | 134.2 | (4.6%) |
| 1997 | $136,826,119 | 136.8 | 2.0% |
| 1998 | $125,679,501 | 125.7 | (8.1%) |
| 1999 | $144,986,258 | 145.0 | 15.4% |
| 2000 | $200,550,000 | 200.6 | 38.3% |
| 2001 | $147,560,000 | 147.6 | (26.4%) |
| 2002 | $138,330,000 | 138.3 | (6.3%) |
| 2003 | $161,970,000 | 161.9 | 17.1% |
| 2004 | $210,320,000 | 210.3 | 29.9% |
| 2005 | $225,540,000 | 225.5 | 7.2% |
| 2006 | $246,020,000 | 246.0 | 9.1% |
| 2007 | $255,470,000 | 255.5 | 3.8% |
| 2008 | $255,990,000 | 256.0 | 0.2% |
| 2009 | $218,480,000 | 218.5 | (14.7%) |
| 2010 thur July | $165,990,000 |

Subscribe to:
Posts (Atom)
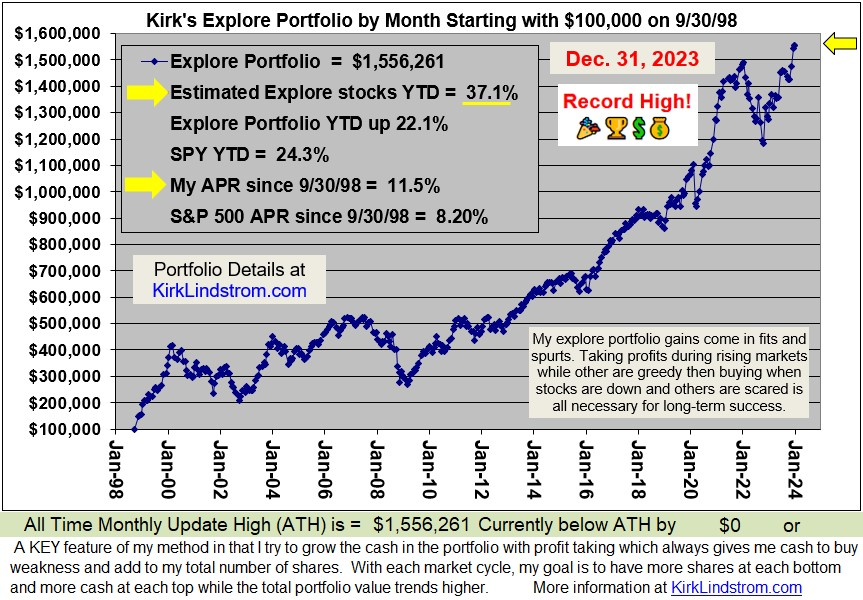
Kirk Lindstrom's Investment Letter Performance
Subscribe To


 Posts
All Comments
 kirklindstrom.com

