Don't Miss Out On Great Gains! - Best Investment Newsletter


Click for FREE sample of Kirk Lindstrom's Investment Letter

Don't miss out! Subscribe Now

google.com, pub-7001134751860982, DIRECT, f08c47fec0942fa0

Search For More

Showing posts with label vrgy. Show all posts

Friday, September 17, 2010

Idea to Create Jobs

Background:  I read cash rich companies like Microsoft (MSFT Charts & Quote) and Cisco (CSCO charts and quote) are BORROWING BILLIONS of dollars to pay dividends and repurchase their stock because much of their cash is overseas.  If they bring the cash back to the US to hire workers here, pay dividends or buy back their own stock, then they are taxed so it is cheaper for them to borrow the money.

Idea #1:  Why not let companies bring their cash made overseas back to the US if used to grow employment here?  That is if they grow their workforce by $1B over 5 yrs (2,000 jobs that pay $100,000 salary over 5 yrs) then they can bring back $1B tax free.  If they reduce their US employment over that 5 yrs, then they have to repay the taxes due.

Idea #2: Even simpler, since dividends are taxed, why not let companies use overseas cash to increase their dividends?  This would be great for IRAs since the dividends would eventually be taxed as ordinary income when savers take the money out.... a good thing for the IRS.

This idea would make it MORE profitable to make money overseas from jobs created in the US.

Without this change, I fear companies like Microsoft, Cisco, Intel, HPQ, etc. (links go to stock quotes and charts)  will use the cash to buy companies outside the US to grow even more outside the US.  If tax policy here remains punishing to job creators, I believe they will eventually leave the US for more tax friendly countries like Verigy (VRGY quote and charts) did after it spun off from Agilent/HP and moved to Singapore.  

FWIW, moving jobs overseas for better tax treatment and lower wages is nothing new.  When I started at Hewlett-Packard as a summer intern in 1978 we were in the process of moving final test of some volume products to Singapore.  By the time I left 20 years later, I was training experienced engineers from Singapore (on temporary visas) to do jobs I trained top engineering graduates from CAL, Stanford and MIT to do ten years before.   It is no accident US jobs moved to where companies can operate at a higher profit.  The US needs to look at how it can reverse the tide and bring jobs back to the US.

What do you think?  Post your thoughts in the Comments Section.

Update 12:40 PM PST:    Details are in comments section:
  1.  Cisco has over $30 billion outside the U.S.  John Chambers said "Easiest way to generate jobs is to bring back the money, Implore people to do that. Of Fortune 100, we may be only one that is growing headcount in the U.S. by 10%."
  2. John Chambers said  repatriation of cash, if it occurs, some will be used for job creation, some to drive up stock prices (probably via buybacks.)  Even buybacks are good for the taxpayer as they will come back to be taxed  as ordinary income when people with stock in their IRAs convert it to cash to take RMDs when they retire.

Thursday, December 06, 2007

Grilled Bear Meat on the Menu

Groundzero posted the following comment in our facebook group "Spiral Forum: Trading Futures with Groundzero Discussions" to Glen's comment "The bears are feeling the heat right about now...."

Yes, and these bears have no idea what is still in store for them over the next few weeks...

GZ (December 6, 2007)
I replied here with the following observation:

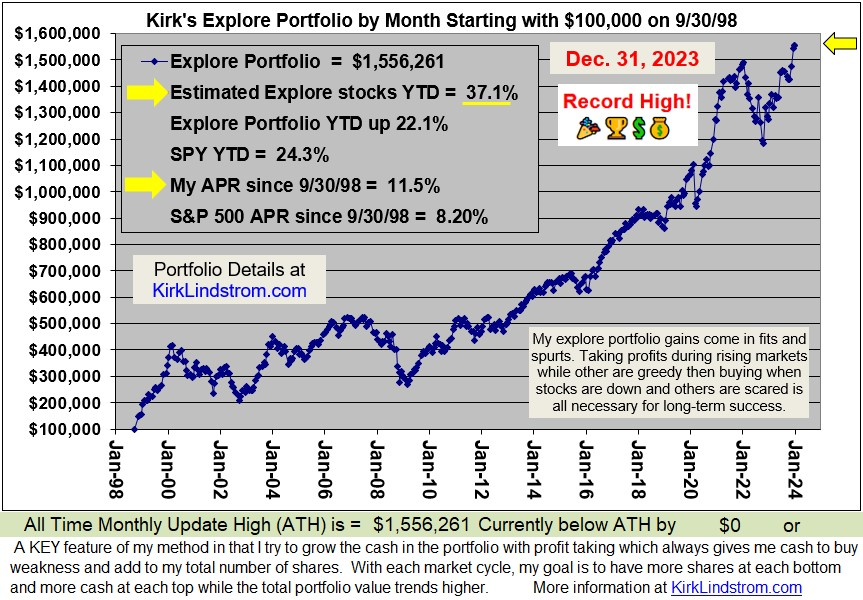
If we come out of the hole like we did in 1998 after we had the big banking bottom in 1998, they will be in deep trouble. I recall my "(newsletter) explore portfolio" (started Sept. 30, 1998) went from being down about 20% in October (1998) to finishing December (1998) at up 58% followed by 117% more in 1999 (performance graph.) I think some of the four letter stocks I like (today) could be on some naked short lists, a new trick by bears to drive prices down.... so if they get insolvent, their broker/dealer backers will have to cover... it could be a bloody mess as some of us stock up grilled bear meat to feast on for the next ten years.
Being "naked short" means someone sold shares they were unable to borrow. Thus, if they are forced to cover short due to a margin call, they will have to go find shares to buy at any price. If you think a short covering rally is big, wait until we see some naked shorts forced to cover.

Recent 10 to 20% one day gains in stocks I have such as VLNC, VRGY and FNSR will look tame to what a naked short rally could look like.

Just think about how much these little stocks could move up if the investing public were to one day return to high risk growth stocks that go up.


Tuesday, September 25, 2007

Value in Growth at Lam Research and Verigy Inc.

Someone with a large position in Warren Buffett’s Berkshire Hathaway (ticker BRKA) asked if he should buy another cash loaded company with similar valuation metrics, Wesco Financial Corp. (WSC). My reply was the real value today is in some small capitalization technology stocks like Lam Research (LRCX) and Verigy (VRGY.) Here is my reasoning.

One of the reasons I have stayed away from Berkshire Hathaway is its “Warren E. Buffett Premium.” This is what people pay to own BRKA over “fair value” so Warren Buffett can manage their money. What happens to the price of BRKA if Buffett dies?

BRKA today reminds me of General Electric (GE) in 2000 when it still had its "Jack Welch Premium" not to mention the daily gushing on CNBC about how much money the reporters were making in the individual stock they could own. In 2000 GE had a PEG (Price-to-earnings ratio divide by its 5-year growth rate) twice that of the S&P500. Today that premium is gone and GE at $41 is still down about 30% from its 2000 peak while the S&P500 is back to its 2000 peak. High premiums are risky.

Selling at $117,200 with $30,343 per share in cash, BRKA is 26% cash. This survey of CD rates says you can get 5.0 to 5.75% at many banks in CDs. If I want to pay a premium for Warren Buffett to manage my money, then I would want his return on assets to beat safe CDs and treasuries enough to overcome this premium at a minimum.

Yahoo! finance lists BRKA’s “management effectiveness” as:

    Return on Assets (ttm): 4.65%
    Return on Equity (ttm): 11.34%
    (ttm is trailing twelve months)


With Valuation metrics:

    Trailing P/E (ttm, intraday) = 14.99
    Forward P/E (fye 31-Dec-08) = 19.35
    PEG Ratio (5 yr expected) = N/A (no earnings growth predicted)
    (fye is for year ending)


Why not put 25% of your money in 5.75% CDs and invest the other 75% in stocks with better GARP (Growth At Reasonable Price) metrics?

Compare the above numbers for BRKA to one of my larger holdings and a company I have already made about sixteen (16!) times my money on since buying it for my newsletter and personal portfolio in 1998, Lam Research (Ticker LRCX.)

Yahoo! finance lists Lam’s “management effectiveness” as:

    Return on Assets (ttm) = 21.21%
    Return on Equity (ttm): 43.29%

With valuation metrics:

    Trailing P/E (ttm, intraday)= 12.24
    Forward P/E (fye 25-Jun-08) = 12.21
    PEG Ratio (5 yr expected) = 0.65

Verigy is another “GARP” stock I have been buying for my newsletter portfolio and myself. Yahoo! finance lists Verigy’s “management effectiveness” as:

    Return on Assets (ttm): 10.38%
    Return on Equity (ttm): 18.48%

With valuation metrics:

    Trailing P/E (ttm, intraday)= 19.96
    Forward P/E (fye 31-Oct-08) = 13.47
    PEG Ratio (5 yr expected) = 0.79

Verigy has a similar cash/share ratio as BRKA but it makes far better returns overall.

I think there is great value now is in technology stocks that are not in the headlines. Everyone knows about Google (GOOG) and Apple (AAPL) but how many have heard of Lam Research or Verigy? The way to make big gains is to buy well managed growth stocks before everyone has heard of them. I have made good money already in both Lam and Verigy but I think there is much more to be made.

In addition, how are people trying to help third world countries improve? Are they giving them cans of Coke (KO) Geico insurance, Sees candy and Gillette razors (PG,) all subsidies of BRKA, or are they giving the kids portable, cheap, laptops with wireless connectivity that operate on the sun or hand cranking? Lam and Verigy are two of my best-valued stocks that make picks and shovels that help make this new technology possible.

BRKA is mostly a perceived "value stock" and we have had about 7 years where investors have shunned growth to buy good, safe value stocks. The numbers I posted above for Lam and Verigy, stocks I buy and sell for added return around a core position, show why I think a rotation to growth with value should occur soon, if it has not already started.

Subscribe now and get my just released October 2007 Newsletter with my two core portfolios plus my more volatile (and higher long term return) explore portfolio with the latest buy and sell targets.

Followers - Click "follow" to get an email alert for new articles

Kirk Lindstrom's Investment Letter Performance