Don't Miss Out On Great Gains! - Best Investment Newsletter


Click for FREE sample of Kirk Lindstrom's Investment Letter

Don't miss out! Subscribe Now

google.com, pub-7001134751860982, DIRECT, f08c47fec0942fa0

Search For More

Showing posts with label GE. Show all posts

Wednesday, September 06, 2017

During Market Turbulence Diversification Works!

Yesterday a subscriber who's worked to get a better asset allocation for her age (after subscribing to my newsletter 2.5 yrs ago in early 2015) was worried about the market and current events sent me this short email.
On 9/5/2017 5:16 PM, RH wrote: 
Hi Kirk;  
The market really looks like it tanked today, right?
OMG, I never really know what to do with next step……
I try to answer all emails, even if they don't have a specific question as I see part of my "service" is to reassure subscribers when they are worried.

Here is part of my reply (removing some personal details for this "edited" reply.)
Remember, one reason we took so many profits and diversified from US stocks that were way up to add to international stocks and build cash is the market often goes down.  You have a LOT of cash now (50:50 conservative asset allocation) so if the market goes down by 10 or 20%, then you could put some of it to work buying stocks at sale prices.
With:

  • an H-bomb tested by the nut in N. Korea plus
  • Hurricane Harvey left hundreds of thousands with huge storm damage in Texas
  • Hurricane Irma is heading towards Florida and it could be even bigger
  • Tropical storm Jose is following Irma and could hit either areas just as they start to recover..... 
yet the stock market was only off about 3% at the low!  Stocks like Finisar and GE really suffered but others that investors love, including Emerging markets (VWO) that we recently bought at much lower prices, continue to do well. 
So... remember that your asset allocation is much better now even with the stock market near record highs!  You've done the work to be ready for a big decline.... yet if the market continues to chug higher, you have enough in to do really well too!
On 9/6/2017 10:24 AM, RH wrote: 
You somehow know me well and give me peace of mind.
Thank you ever so much.
Nobody likes to see stocks they own go down but with proper asset allocation and diversification, big declines are great opportunities to increase your overall market return.

Lets say you retire with a $1,000,000 investment portfolio.  To sleep well at night you put half into fixed income and half into stocks according to my "Conservative Core Portfolio."  If the stock market drops 50%, which is has twice since the year 2000, then you would have roughly $750,000 and probably more because your fixed income on the conservative side of the portfolio would continue higher and your stock portfolio (ETFs or individual stocks) would continue to pay dividends.  

I'd use the 50% bear market to significantly add stocks to my Explore Portfolio (as I did during both bear markets.)  I would also do a MINIMUM of one portfolio reallocation from fixed income to stocks at the end of the year if stocks were still down just as last January I moved a great deal of cash out of markets that were way up in the Core Portfolios to fixed income to lock in gains.

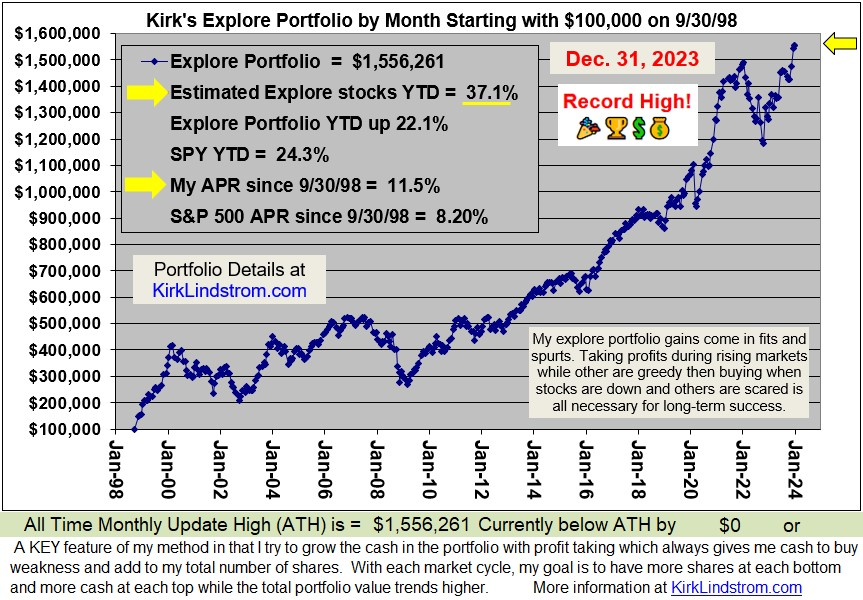
If you need references to verify I took profits when the markets were up and bought when they were down to get the returns I post, then I am happy to provide them.  It blows me away that so many sell their newsletter services and don't provide simple return tables and graphs like I do below.  That is a RED FLAG WARNING about what they sell.


Kirk Lindstrom's Investment Letter
 Subscribe NOW and get the September 2017 Issue for FREE!!!
(Your 1 year, 12 issue subscription with SPECIAL ALERT emails will start with November issue.)
VWO Buy Alert Sent via Email
VWO Today 


-end-

Friday, April 10, 2015

Major GE Changes & Record $50B Share Buyback

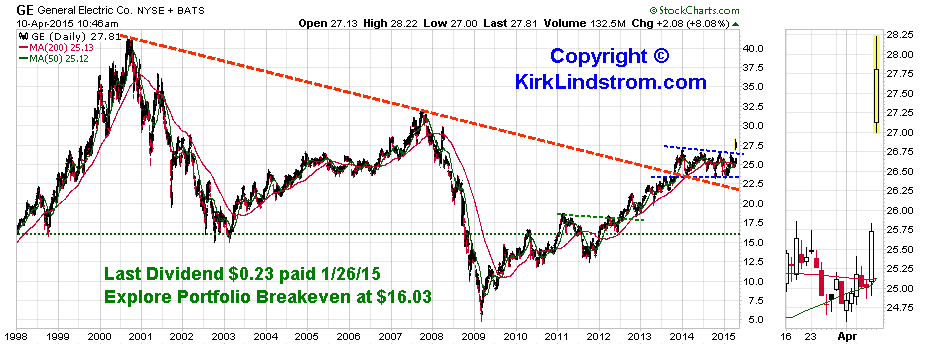
Today GE (my GE charts and price quote) announced a major change in the structure of the company. I reposted the press release below with highlights.  Key to me is GE will sell most of its GE Capital assets and use $50 billion of the proceeds to buy back its shares.  GE Capital is a very large bank.  Since the financial crisis, banks get very low PE multiples so GE probably doesn't get the PE multiple it could without GE Capital. GE Capital is profitable so someone like a private equity firm with cash earning near zero might find GE Capital a wonderful investment.

CNBC said this $50B ties Apple for the largest share buyback in history.  Investors love this news as GE's stock price is up over 8%.

GE was one of the stocks I bought at the very bottom of the financial crisis.
Original PDF file: GE March 4 Buy Alert at $6.76
Details of today's announcement (Original Press Release)
GE TO CREATE SIMPLER, MORE VALUABLE INDUSTRIAL COMPANY BY SELLING MOST GE CAPITAL ASSETS; POTENTIAL TO RETURN MORE THAN $90 BILLION TO INVESTORS THROUGH 2018 IN DIVIDENDS, BUYBACK & SYNCHRONY EXCHANGE
  • High-value industrials to comprise more than 90% of GE earnings by 2018
  • Plans to retain financing “verticals” that relate to GE’s industrial businesses
  • Announces sale of GE Capital Real Estate assets for approximately $26.5 billion
  • Will work with regulators to terminate GE Capital’s SIFI designation
  • GE to take approximately $16 billion after-tax charge in 1Q’15, $12 billion non-cash
  • Industrial businesses remain on track for operating earnings per share of $1.10-$1.20 in 2015, in line with expectations
  • GE expects to get approximately $35 billion in dividends from GE Capital from this plan
  • Board authorizes new buyback program of up to $50 billion
FAIRFIELD, Conn. – April 10, 2015 – GE [NYSE:GE] today announced that it will create a simpler, more valuable company by reducing the size of its financial businesses through the sale of most GE Capital assets and by focusing on continued investment and growth in its world-class industrial businesses.
GE and its Board of Directors have determined that market conditions are favorable to pursue disposition of most GE Capital assets over the next 24 months except the financing “verticals” that relate to GE’s industrial businesses.  Under the plan, the GE Capital businesses that will remain with GE will account for about $90 billion in ending net investments (ENI) excluding liquidity – about $40 billion in the U.S. – with expected returns in excess of their cost of capital.
“This is a major step in our strategy to focus GE around its competitive advantages,” GE Chairman and CEO Jeff Immelt said.  “GE today is a premier industrial and technology company with businesses in essential infrastructure industries.  These businesses are leaders in technology, the Industrial Internet and advanced manufacturing.  They are well-positioned in growth markets and are delivering superior customer outcomes, while achieving higher margins.  They will be paired with a smaller GE Capital, whose businesses are aligned with GE’s industrial growth.”
“The successful IPO of GE’s retail finance business, Synchrony Financial, and other recent business exits have demonstrated that our financial services assets can be more valuable to others,” said GE Capital Chairman and CEO Keith Sherin.  “GE Capital’s businesses are excellent, and this is a great market for selling financial assets. Our people are world-class.  We are confident these businesses will thrive elsewhere.”
As part of the execution of this new plan, GE announced today an agreement to sell the bulk of the assets of GE Capital Real Estate to funds managed by Blackstone.  Wells Fargo will acquire a portion of the performing loans at closing.  The Company also has letters of intent with other buyers for an additional $4 billion of commercial real estate assets.  In total, these transactions are valued at approximately $26.5 billion.  
Under the plan, GE expects that by 2018 more than 90 percent of its earnings will be generated by its high-return industrial businesses, up from 58% in 2014.
In 2015, GE’s industrial businesses remain on track for operating earnings per share of $1.10-$1.20, up solid double digits, in line with expectations.  “With sustainable growth, investments in competitive advantage, productivity programs and the addition of Alstom, we expect this performance to continue in the future,” Immelt said.  “We will focus our efforts on these businesses.”
Immelt added, “We are completing another definitive and important move to reshape GE for the future. GE is a fast-growth, high-tech industrial company, built on the capabilities of the GE Store.  The team is executing a detailed plan to boost margins and returns.  We are allocating capital to grow the Company and benefit investors.  Our best days are ahead.”
Creating Value in GE Capital
GE Capital has been an important part of the history of GE.  However, the business model for large, wholesale-funded financial companies has changed, making it increasingly difficult to generate acceptable returns going forward.
GE will retain its “vertical” financing businesses – GE Capital Aviation Services, Energy Financial Services and Healthcare Equipment Finance – that directly relate to its core industrial businesses.  The assets targeted for disposition, in addition to Real Estate, are most of the Commercial Lending and Leasing segment, and all Consumer platforms, including all U.S. and international banking assets.
These businesses represent roughly $200 billion in ENI.  Since 2008, GE has reduced GE Capital’s ENI from $538 billion to $363 billion at the end of 2014.  The separation of Synchrony Financial, which is targeted by the end of 2015, and other recently announced dispositions, account for another $75 billion in ENI reduction (the Synchrony separation is subject to regulatory approval).
There is potential to return more than $90 billion to investors in dividends, buyback and the Synchrony exchange through 2018.  The exits of the targeted GE Capital businesses should release approximately $35 billion in dividends to GE (subject to regulatory approval), which, under GE’s base plan, are expected to be allocated to buyback; this is in addition to the impact of the Synchrony exchange and ongoing dividends.  The GE Board has authorized a new repurchase program of up to $50 billion in common stock, excluding the Synchrony exchange.  GE expects to reduce its share count to 8-8.5 billion by 2018.  These actions would still allow room for opportunistic “bolt on” acquisitions in GE’s core markets.  GE also said it plans to maintain its dividend at the current level in 2016 and grow it thereafter.
Working with Regulators
GE has discussed this plan, aspects of which are subject to regulatory review and approval, with its regulators and staff of the Financial Stability Oversight Council (FSOC).  GE will work closely with these bodies to take the actions necessary to de-designate GE Capital as a Systemically Important Financial Institution (SIFI).  “We have a constructive relationship with our regulators and will continue to work with them as we go through this process,” Immelt said.
Financial Details
Approximately $16 billion of after-tax charges are expected to be recorded in the first quarter of 2015 in connection with the plan – of which about $12 billion are non-cash.  The charges include taxes on repatriated earnings, asset impairments due to shortened hold periods, and charges on businesses held for sale, including goodwill allocation.
GE expects that the earnings impact of the GE Capital exits will be offset by the buyback over the exit period.
GE will execute this strategy using an efficient approach for exiting non-vertical assets that works for GE and for GE Capital Corporation (GECC) debtholders and GE shareholders.  An element of this approach involves a merger of GECC into GE and the creation of a new intermediate holding company for GECC businesses.
GE has amended its income maintenance agreement to guarantee all tradable senior and subordinated debt securities and all commercial paper issued or guaranteed by GECC.  The guarantee will replace the current income maintenance covenant.  GE will maintain substantial liquidity and capital through the transition and does not expect to issue incremental GE Capital long-term debt for at least five years.  Commercial paper will be further reduced to approximately $5 billion by the end of 2015.
“We are proud of the GE Capital team, the outstanding businesses that GE Capital employees have built, and how they have delivered for customers and shareholders over many years,” said Immelt.  “The GE Capital team has displayed great resiliency, facing tough cycles and driving strong results.”
J.P. Morgan and Centerview Partners have provided financial advice to GE, and Bank of America provided advisory services.  Weil, Gotshal & Manges, Davis Polk, and Sullivan & Cromwell provided legal advice.  For the Real Estate deal, Bank of America and Kimberlite Advisors provided financial advice and Hogan Lovells provided legal advice. 
GE will discuss this announcement on a webcast at 8:30 a.m. ET today, available atwww.ge.com/investor.  Related charts will be posted on our website for your review prior to the call.
About GE
GE (NYSE: GE) imagines things others don’t, builds things others can’t and delivers outcomes that make the world work better. GE brings together the physical and digital worlds in ways no other company can. In its labs and factories and on the ground with customers, GE is inventing the next industrial era to move, power, build and cure the world. www.ge.com
GE’s Investor Relations website at www.ge.com/investor and our corporate blog at www.gereports.com, as well as GE’s Facebook page and Twitter accounts, including @GE_Reports, contain a significant amount of information about GE, including financial and other information for investors.  GE encourages investors to visit these websites from time to time, as information is updated and new information is posted.
Caution Concerning Forward-Looking Statements:
This document contains “forward-looking statements” –.... yadda yadda yadda (read more at Original Press Release)
Learn the "Core and Explore" approach to investing
with "Kirk Lindstrom's Investment Letter"


Subscribe NOW and get the April 2015 Issue for FREE!  
(Your 1 year, 12 issue subscription will start with next month's issue.)


Wednesday, March 03, 2010

FNSR: Finisar up 571% Over Past Year

A year ago today I added to my Finisar (Ticker FNSR Chart and Quote) holdings at 24¢ (This is $1.92 at today's split adjusted price)

See PDF file: Finisar Mar 3 Buy Alert at 24¢

Today Finisar is $12.89!! (or $1.61 at the pre-split price)

The Gain is (12.89-$1.92)/$1.92x100% = 571%!

What were you doing a year ago? Buying or selling?

Going forward, I still like Finisar and hold it in both new personal and newsletter explore portfolios.

Excerpts from the March issue of "Kirk Lindstrom's Investment Letter" about Finisar:

On Feb 9 Finisar said it expects to report revenues of $166 to $167M for its fiscal Q3 ended January 31, 2010. Its prior revenue guidance was $148 to $158M. In the absence of a material adjustment, Q3 revenues will set a new record for Finisar surpassing the previous combined sales for Finisar and Optium of approximately $163M for the fiscal quarter ended July 31, 2008, just prior to the merger of the two companies and the market melt-down. Based on these projections, Finisar expects to be at the upper end of its original guidance for Q3 on a non-GAAP basis of 30%-32% for gross margin and 6%-8% for operating margin. Sequential revenues will be up about 14.3% over Q2-2010 and 32.1% over last year, Q3-2009! This is the great performance I expected and expect to continue. It is why I bought so many shares of Finisar during the downturn.

6%-8% operating margin on $166 to $167M revenue implies earnings between $10.0M and $13.4M or 15¢ to 21¢ per share.

Finisar should continue to grow operating margin as the costs from merging with Optium end and the new efficiencies take hold. Margins will also improve with volume which I predict will continue to grow at a high rate for many years, subject to gyrations of the economic cycle.

I think FNSR could easily do $1.00 per share in 2011 where a PE of 20 for their growth would be very reasonable. Add in some exuberance as others jump on the bandwidth-wagon and a PE of 40 would be a good target to take major profits at. I find it amazing that FNSR is still cheap with a PE of only 13.5 on FY 2011 earnings. FY2011, only months away, is when we will get FY2012 earnings estimates that should be significantly higher. I expect we will see $20 in a year, if not sooner.

Click table to see full size image

My only regret is I didn't buy even more!

I actually bought Finisar shares 6 different times at prices lower than today.

After buying when very low, I took some profits when it soared. Then I bought some back on a correction. Now I and am back to taking profits, a little at a time, as I hope it continues higher.

If Finisar corrects enough, I may buy shares back again unless my opinion on Finisar changes and I sell all shares.

Disclaimer: I own FNSR in my personal and newsletter portfolios. I may trade around a very profitable core position at any time. I often have buy and sell targets in my newsletter where I announce "Auto Buys" and "Auto Sells" (limit orders with your broker) ahead of time.

Note: A day later I bought some GE at $6.76. See
Give it time to load as it is pdf on a slow server.

Click for full size image courtesy of stockcharts.com

Current FNSR Chart and Quote


Wednesday, January 20, 2010

Ultratech to Share DOE Grant for Solid State Lighting

Ultratech Inc, (UTEK charts) will share a $23.5M Department of Energy (DOE) grant with Applied Materials (AMAT Charts), GE Global Research (GE Charts), GE Lumination, KLA-Tencor Corporation (KLAC), Philips Lumileds Lighting Company, Universal Display Corporation (UDC) and Veeco Instruments as part of the American Recovery and Reinvestment Act to support manufacturing high-efficiency solid-state lighting projects.

"Low-Cost Lithography Tool for High-Brightness LED Manufacturing"

Ultratech, with team member SemiLEDs, will attempt to develop a lithographic manufacturing tool with the benefits of higher throughput, greater yields, lower initial capital cost, and lower cost of ownership. Ultratech will modify a projection stepper process used for larger wafers and optimize it for LED manufacturing. The proposed new manufacturing tool will be able to accommodate a variety of wafer sizes and thicknesses and handle the wafer warpage typically associated with larger-diameter wafers.

From DOE Announces Selections for SSL Core Technology (Round 6), Product Development (Round 6), and U.S. Manufacturing (Round 1) Funding Opportunities

These eight selections

"are focused on achieving significant cost reductions and enhancing quality through improvements in manufacturing equipment, processes, or monitoring techniques. Projects address the technical challenges that must be overcome before prices fall to a level where solid-state lighting will be competitive with existing lighting on a first-cost basis. The total value of manufacturing selections is $23.5 million; the performers will provide an average of 51 percent as cost-share.

A major DOE objective in funding these projects is to develop, establish, and/or maintain the solid-state lighting technology and manufacturing base within the U.S., which will create jobs and promote our nation's role as a leader in the field. "


Ultratech has said during conference calls it now sells a new, low cost (under $1M) solder bump stepper for small wafers (probably between 1 and 3 inches) used for white LEDs that will replace incandescent and fluorescent lights. Ultratech said it expects this market for efficient visible LEDs to grow 35% per year starting in 2010.

To get costs down, manufactures will want to use larger wafers similar to how microprocessors and other silicon based semiconductors grew from 3-inches in diameter 30 years ago to 12 inches today.

Disclaimer: I own and trade UTEK around a core position in both my personal account and in my newsletter with a very low cost basis. My newsletter "Explore Portfolio" currently has a break-even cost of $2.91 per share for UTEK where I have set prices already announced for selling shares. I may buy or sell shares at any time so beware. I also own AMAT and GE in both my personal account and my newsletter explore portfolio.

Subscribe to Kirk's Investment Newsletter today to get my current outlook for UTEK , AMAT and GE including buy and sell levels to trade around a core positions in many of the stocks I follow.

Since 12/31/98 "Kirk's Newsletter Explore Portfolio" is UP 159% (a double plus another 59%!!) vs. the S&P500 UP a tiny 8.6% vs. NASDAQ UP a tiny 3.5% (All through 12/31/09) (More info - FREE Sample Issue)

Subscribe NOW and get the January 2010 Issue for FREE!
(Your 1 year, 12 issue subscription will start with next month's issue.)


Thursday, December 17, 2009

Top Stock Offerings in History

The top five secondary stock offerings on record in the US according to CNBC and Dealogic are
  1. $19.3B: Bank of America (BAC charts & Quote)
  2. $17B: Citigroup (C charts & Quote) Today!
  3. $12.65B: Wells Fargo Bank (WFC charts & Quote)
  4. $12.25B: Wells Fargo Bank
  5. $12.2B: General Electric (GE charts & Quote)
One way to get the banks in a single investment is with the exchange traded fund XLF (XLF charts and quote).

I added to my profitable newsletter position in Citi today when it was under $3.20. I sent an email to my subscribers announcing this buy when Citi was at $3.16. My last action before that was to buy shares at $2.95 when it was unclear if Citi would survive. With dividends included, I am on "house money" with Citi meaning that the sum of all my buys less money from selling higher priced shares and dividends is a positive number.

click chart courtesy of stockcharts.com for full size image

Since 12/31/98 "Kirk's Newsletter Explore Portfolio" is UP 155% (a double plus another 55%!!) vs. the S&P500 UP at tiny 7.4% vs. NASDAQ Down 0.2% (All through 12/17/09) (More info & FREE Sample)

As of December 10, 2009, "Kirk's Newsletter Explore Portfolio" is up 32% YTD vs. DJIA up 18% YTD

Subscribe NOW and get the December 2009 Issue for FREE! !
(Your 1 year, 12 issue subscription will start with next month's issue.)

For more information, see:

Disclosure:
I own Citi, GE and XLF in my personal account and my "Newsletter Explore portfolio."

Friday, April 11, 2008

GE Misses and Consumer Confidence at 26-Year Low

General Electric Company (GE Charts) and The University of Michigan's consumer sentiment index woke the markets with a shocking one-two punch this morning. GE's stock fell over 11% in the first hour of trading while consumer confidence fell to the lowest level since March 1982!

GE shocked the market by missing its earnings estimate in a big way this AM (Press Release).

  • GE revenue was up 8% to $42.24 billion from $39.20 billion, with global revenue up 22%

  • Net income fell 6% to $4.3 billion, or 43¢ per share, from $4.57 billion, or 44¢ per share, a year ago. Analysts had expected 51¢ a share and GE had forecast profit of 50 to 53¢ per share.

  • GE lowered earnings per share guidance for all of 2008 to $2.20 - 2.30, up 0 to 5% over 2007. Analysts were expecting GE would earn $2.43 for all of 2008.

Click graph courtesy of Bigcharts.com to view full sized

Jeff Immelt in the earnings conference call said:

  • “Our primary shortfall was a decline in financial services earnings. We knew the first quarter was going to be challenging, but the extraordinary disruption in the capital markets in March affected our ability to complete asset sales and resulted in higher mark-to-market losses and impairments."

  • "We are lowering our full-year EPS guidance to $2.20-2.30 from continuing operations reflecting growth of 0-5%. As a part of this guidance, we expect our industrial earnings to grow 10-15% and financial services earnings to decline 5-10%... Consistent with this range, our second quarter 2008 guidance is $.53-.55 EPS.”

Prior to today, GE was known for meeting its estimates every quarter.

Good news was total orders rose 8% in the period and that major equipment backlog jumped 41%, so it's not as if business just ground to a halt. Business outside the US was growing strong but that could slow if the recession in the US spreads to other economies.

Click graph courtesy of Stockcharts.com to view full sized

The University of Michigan's U.S. consumer sentiment index fell to 63.2 in April from 69.5 March. This is the lowest level since March 1982.

Click graph courtesy of Martin Capital to view full sized


In January we published "ECRI Says There Is A Window of Opportunity for the US Economy" where readers were asked to envision the economy as a large Roman stone column that had just started to topple. ECRI postulated that "prompt stimulus to boost consumer spending" could prevent the column from tipping over into a recession. With today's news from GE and the University of Michigan, we've heard two loud THUDS as two columns hit the dust.

Disclaimer. I personally own and recommended GE in "Kirk Lindstrom's Investment Newsletter" where I may buy and sell around a core position.

Wednesday, March 12, 2008

GE: General Electric's CEO Immelt Invests Another $5 Million Of His Own Money In GE Stock

Following insider buying can be a great way to make money even in a falling market. Major insider buying at General Electric (GE) could yield similar gains to patient investors as we have seen with Valence Technology (VLNC).

Yesterday number one insider at General Electric, chief executive officer Jeffrey Immelt, bought 62,000 more shares of GE stock worth $2.04 million at an average price per share of $32.93 according to SEC filings. Immelt told investors that GE should outperform the Standard & Poor's 500 index this year in a "challenging'' environment.

In an annual letter to shareholders released today, Immelt wrote:

  • "You could try to pick the perfect investment for this environment, but it would be a challenge."
  • " Maybe it is in technology, or emerging markets, or commodities, or Treasury bills. Or you could pick GE."

At $34.00, GE has a market cap of $340 billion with a dividend yield of 3.90%. Ten year US Treasury bonds only yield 3.56%.

On why GE won't sell NBC:

  • "We are in a good cycle, with momentum around the Beijing Olympics, the U.S. elections, and the 2009 Super Bowl," Immelt said. "NBCU benefits from GE's global footprint, financial strength, and human resource skills."

NBC profits were up 6 percent in 2007 on 5 percent lower revenue of $15.4 billion.

Immelt's $2 million investment in his companies stock follows a February 29 purchase of 90,000 shares at an average price of $33.42 worth $3.01 million.

Here is a 5-year summary of insider trading by Jeffrey Immelt and a graph.


Insiders usually sell stock as their stock options vest then expire. Exercising stock options reduces shareholder equity to reward insiders for good work, or so the theory goes. They would be foolish to not take advantage of this shareholder generosity so tracking insider selling is not as useful as tracking insider buying.

When insiders use a significant amount of their own money to significantly increase their holdings in the company they work at, then we should pay attention. Valence Technology is a stock with significant insider buying that has recently doubled. This chart of VLNC insider buying is from the Feb. 22, 2008 article "CSCO: Open Letter to Cisco's Board of Directors."


Valence is one of many technology stocks that have been in a prolonged bear market decline after peaking in early 2004. That didn't stop insiders from buying and now they are being rewarded.

I believe GE will eventually offer similar rewards for patient investors.

GE is a great international play as more than half its sales come from outside the US with about $40 billion of the $195 billion total coming from emerging markets.

In the 1976 movie "All the President's Men" on how to uncover the details of the Watergate scandal, Deep Throat told reporter Bob Woodward "I'll keep you in the right direction if I can, but that's all. Just... follow the money."

Discuss this article and GE in general at our facebook "Investing for the Long Term" forum called GE: General Electric "We Bring Good Things to Life"

Disclaimers:

  1. I own GE in my personal account with a 13% profit considering reinvested dividends. I have also hold GE in my newsletter explore portfolio with similar gains.
  2. I own VLNC in my personal and newsletter explore portfolio with gains in excess of 100%. I have taken some profits and have targets to take more profits should it go higher.

Followers - Click "follow" to get an email alert for new articles

Kirk Lindstrom's Investment Letter Performance